Fragmented, essential,
and under-consolidated.
Water treatment M&A across the United States — building scale in a market where scale is scarce and regulation is tightening.
Regulation is forcing capital
into a fragmented market.
U.S. water and wastewater treatment is served by thousands of small operators, municipal systems, and family-owned service businesses. Very few have the balance sheet or the technical capability to absorb the compliance capex that tightening standards — PFAS chief among them — now require.
That combination is the classic consolidation setup: essential service, inelastic demand, regulatory-driven capex, and a seller base without access to institutional capital. The returns come from operational integration and procurement scale, not from financial engineering.
NorthWater pursues platform acquisitions and bolt-ons in treatment and treatment services, and advises owners of these businesses where the alternative is funding a compliance program alone.
Where we focus.
Buy-and-build in treatment
Acquiring a platform with credible management and real integration capacity, then building through disciplined bolt-ons rather than a single large bet.
Recurring contracted revenue
O&M, monitoring, and specialty treatment businesses with contracted recurring revenue and regulatory-driven demand.
PFAS and emerging contaminants
Situations where a tightening standard creates a capital requirement the incumbent owner cannot fund alone — and where that requirement is the transaction.
Owner-operators and families
Advising founders and families on process, valuation, and counterparty selection when the decision is to transact rather than to recapitalize.
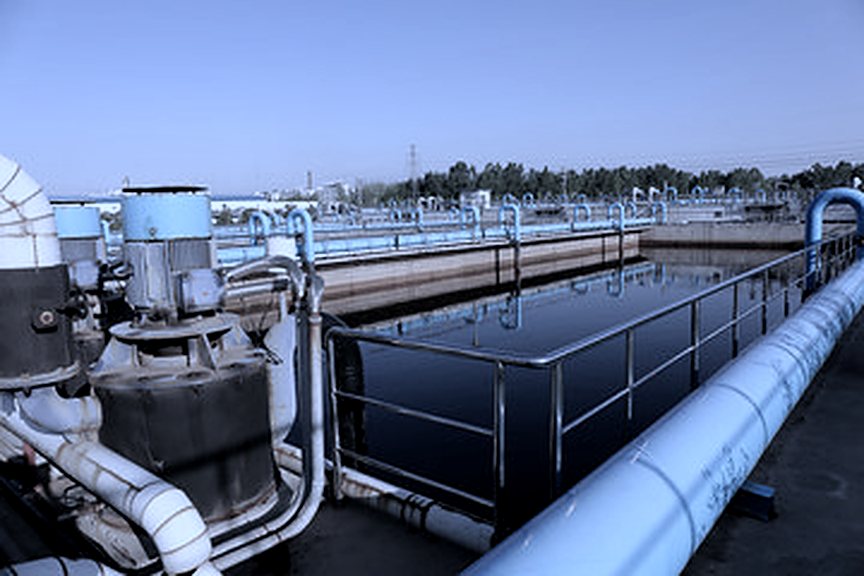
On the ground.
The other three verticals.
Conventional and competitive generation across the full United States — merchant markets and utility-dominant regulated jurisdictions alike.
Data center power co-development nationwide, spanning competitive and regulated markets. Power-first origination, not confined to a single ISO.
Differentiated midstream, deliberately outside competitive mainstream midstream: islanded markets, adjacent services, and power-integrated CO2.
Bring us a situation.
We look at power, digital infrastructure, water, and midstream opportunities across the United States — as principal, co-developer, or adviser.