Midstream, deliberately
off the beaten path.
Differentiated midstream positioned outside competitive mainstream midstream — islanded markets, adjacent services, and power-integrated CO2.
We do not compete where
capital is abundant.
Mainstream midstream is efficiently priced and heavily banked. Basin takeaway and major pipeline assets attract capital that will accept lower returns than we will, and we have no advantage there.
Where we do have an advantage is in markets and structures mainstream capital finds awkward: geographies with no pipeline access, service lines adjacent to the core logistics asset, and power infrastructure integrated into a CO2 or EOR footprint. These are smaller, more operationally involved, and harder to underwrite from a screen — which is precisely why the returns are there.
NorthLogistics is built around three specific theses rather than a general midstream mandate.
Three focus areas.
Rail as synthetic pipeline
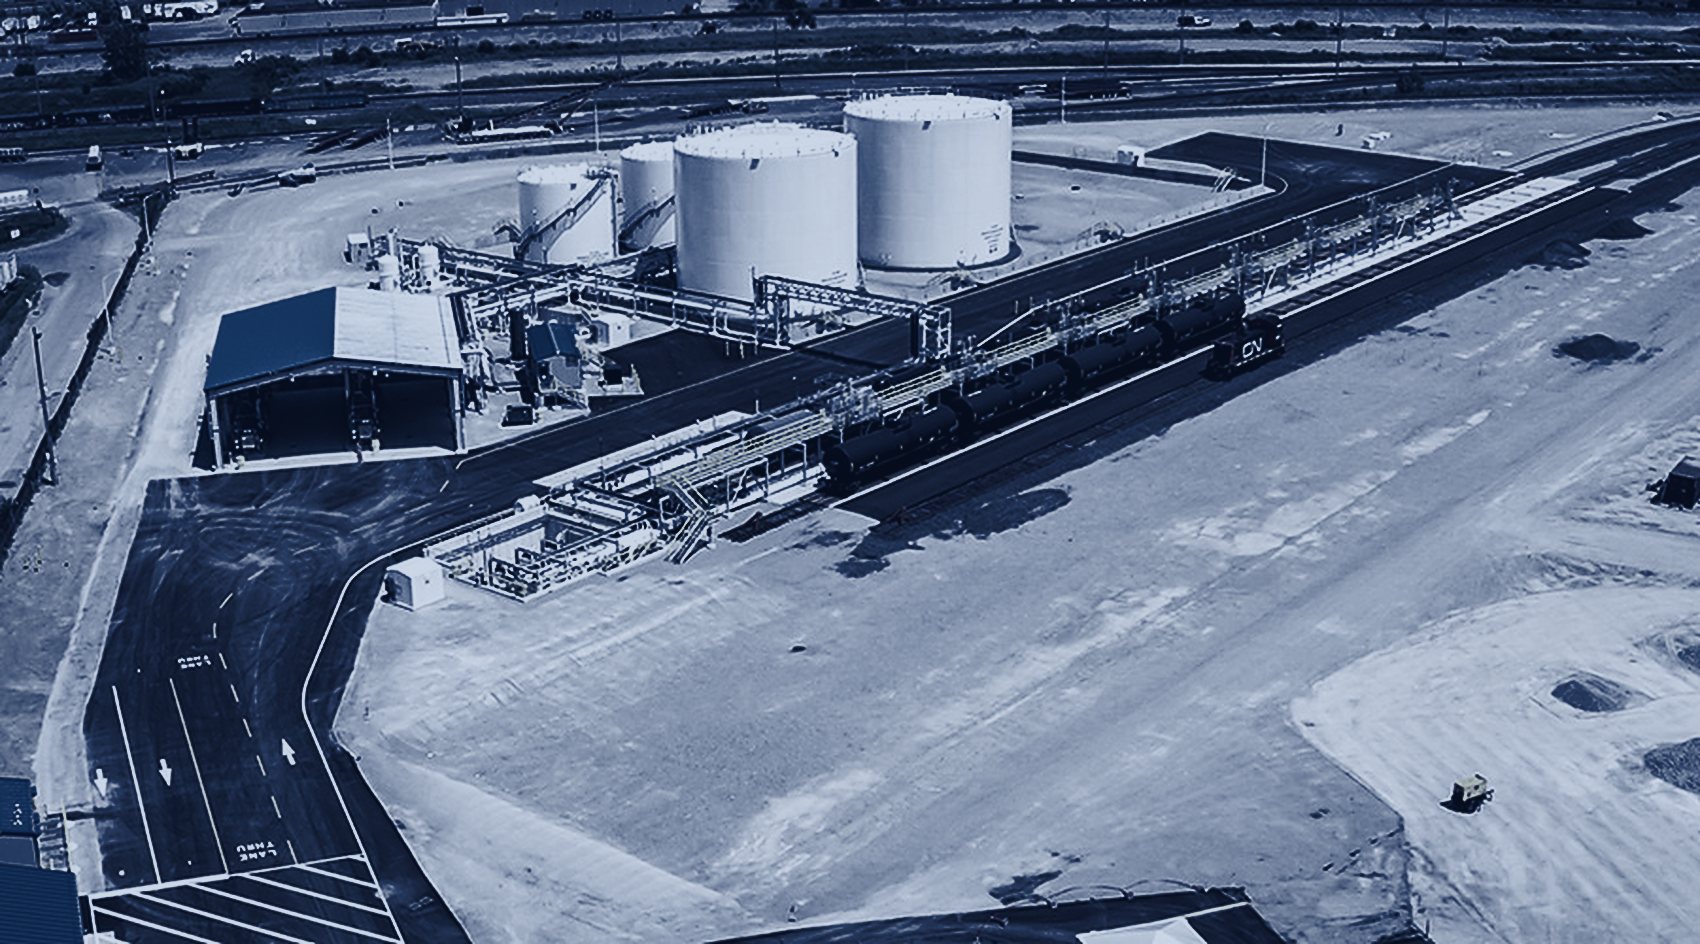
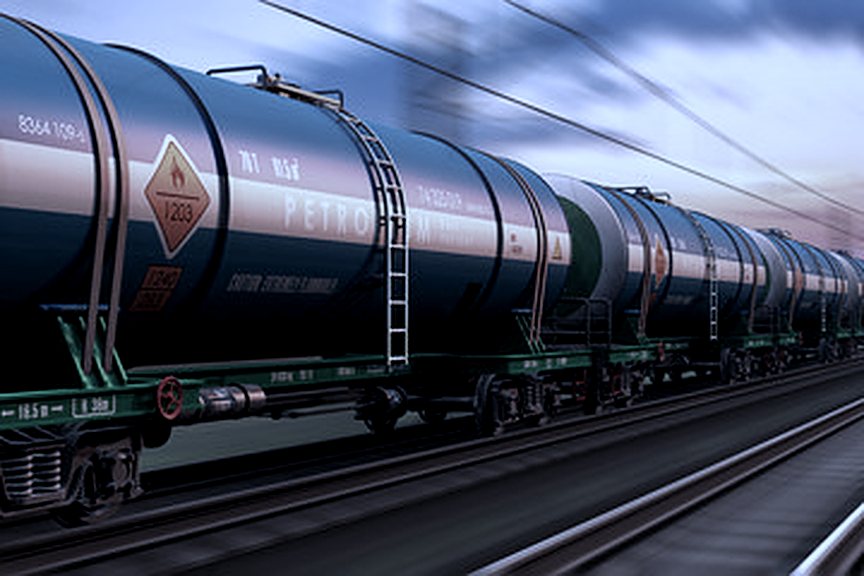
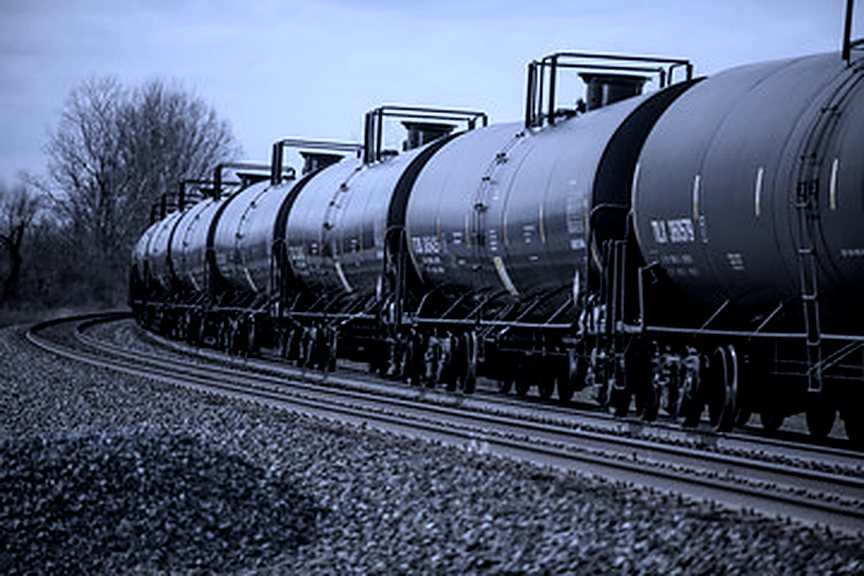
Refined products delivery by rail into markets with no pipeline access — Florida and the Desert Southwest chief among them. A unit-train system functions as a synthetic pipeline where a pipeline will not be built.
Water collection and treatment
Expanded and adjacent service lines around the core logistics footprint, including water collection and treatment, where the terminal or corridor asset already creates the customer relationship.
Generation along CO2 corridors
Power development integrated with CO2 infrastructure and EOR-adjacent activity, including generation sited along established CO2 routes.
Return, not scale
Each thesis sits deliberately outside the competitive mainstream. The objective is return per unit of risk in a defensible niche, not asset-base growth.
Where a pipeline
will not be built.
Florida and the Desert Southwest consume refined products at scale with no pipeline access. A dedicated unit-train system does the same job, at a return mainstream midstream capital will not chase.
On the ground.
The other three verticals.
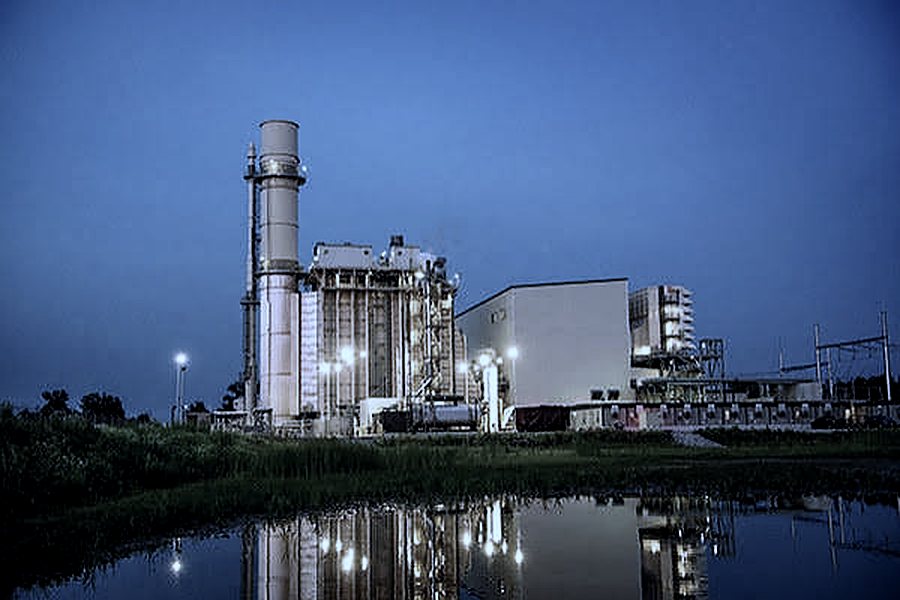
Conventional and competitive generation across the full United States — merchant markets and utility-dominant regulated jurisdictions alike.
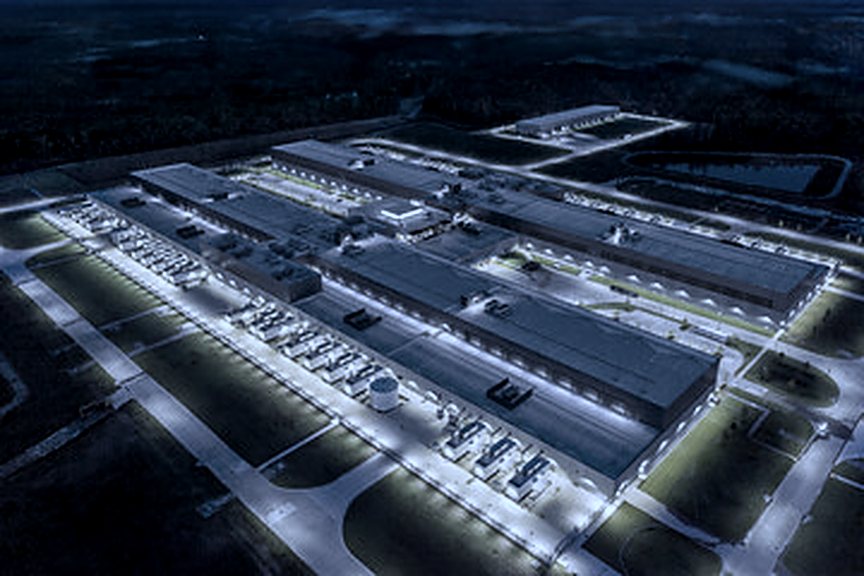
Data center power co-development nationwide, spanning competitive and regulated markets. Power-first origination, not confined to a single ISO.
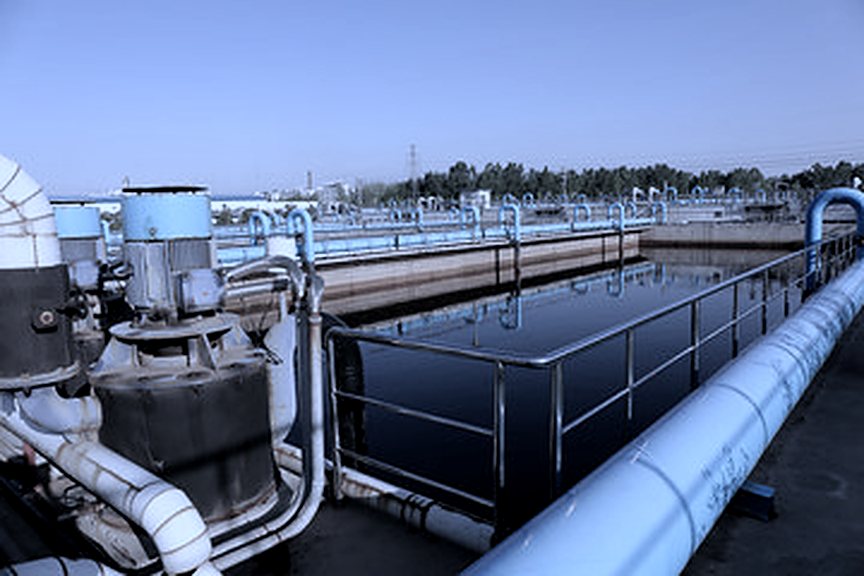
Water treatment M&A — consolidation and platform building in a fragmented, regulation-driven U.S. market.
Bring us a situation.
We look at power, digital infrastructure, water, and midstream opportunities across the United States — as principal, co-developer, or adviser.