Data centers are
a power problem.
Data center power co-development across the full United States, spanning competitive and regulated markets. Not confined to a single ISO.
The constraint moved from
concrete to electrons.
Hyperscalers and AI operators are committing tens of billions to external compute infrastructure — a structural shift away from build-it-yourself. What they cannot procure at the same pace is firm, deliverable power on a schedule that matches the compute deployment.
That gap is the opportunity. Shell and fit-out capital is abundant and competitively priced. Power capacity with a credible energization date is not. The scarce skill is not building the hall — it is assembling generation, interconnection, and site into a package a hyperscaler can actually contract against.
NorthDigital co-develops that package with site owners, developers, and generation counterparties, and is deliberately not limited to any one market. The best answer is as often in a regulated jurisdiction as a competitive one.
Where we focus.
Power-first site development
We start from deliverable power and work toward the site, rather than optioning land and hoping interconnection follows.
Partnering with DC developers
Joint ventures with data center developers and site owners who have the real estate and the customer relationships but need the power solution and the capital behind it.
On-site and phased supply
Behind-the-meter and bridge generation structures that let a campus energize ahead of the grid interconnection date, then transition.
Utility-jurisdiction structures
Structures suited to utility-dominant markets, where the path runs through the utility and the commission rather than an ISO queue.
Capacity is not a
date.
A megawatt figure in a term sheet is worth what its energization schedule is worth. We underwrite the date, the interconnection position behind it, and the generation that has to be there when the racks arrive.
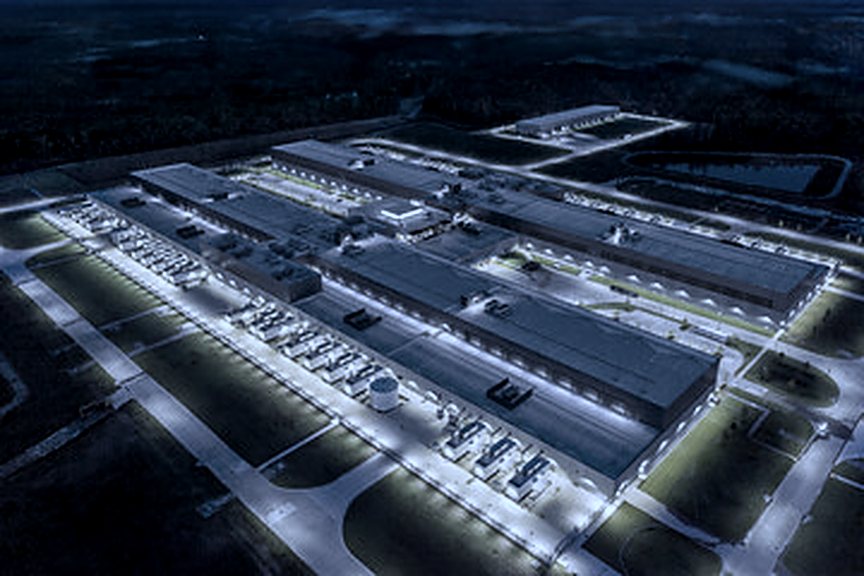
On the ground.
The other three verticals.
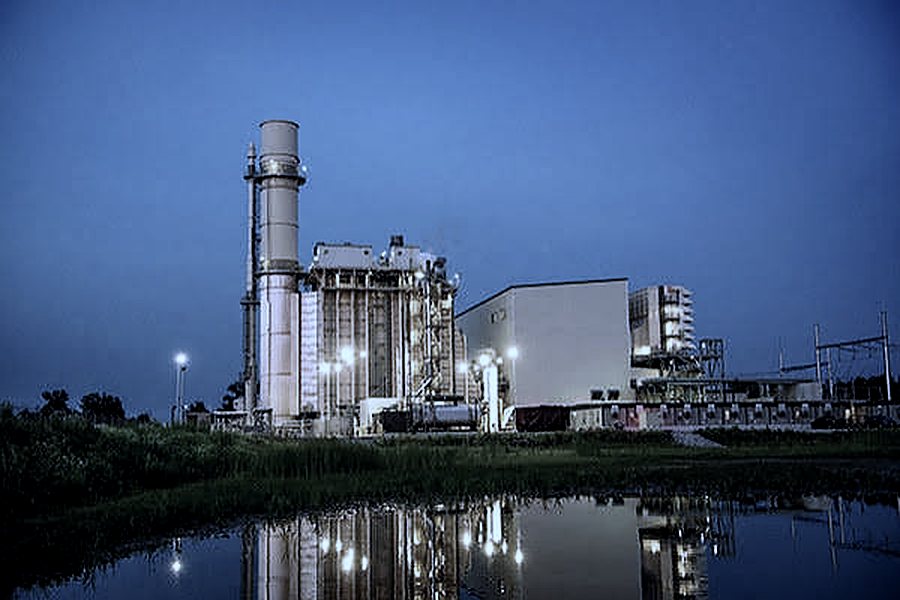
Conventional and competitive generation across the full United States — merchant markets and utility-dominant regulated jurisdictions alike.
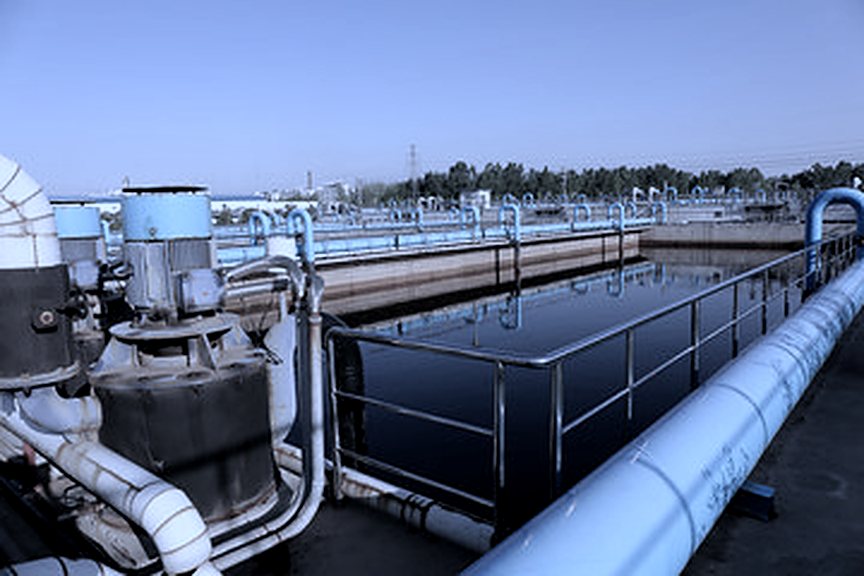
Water treatment M&A — consolidation and platform building in a fragmented, regulation-driven U.S. market.
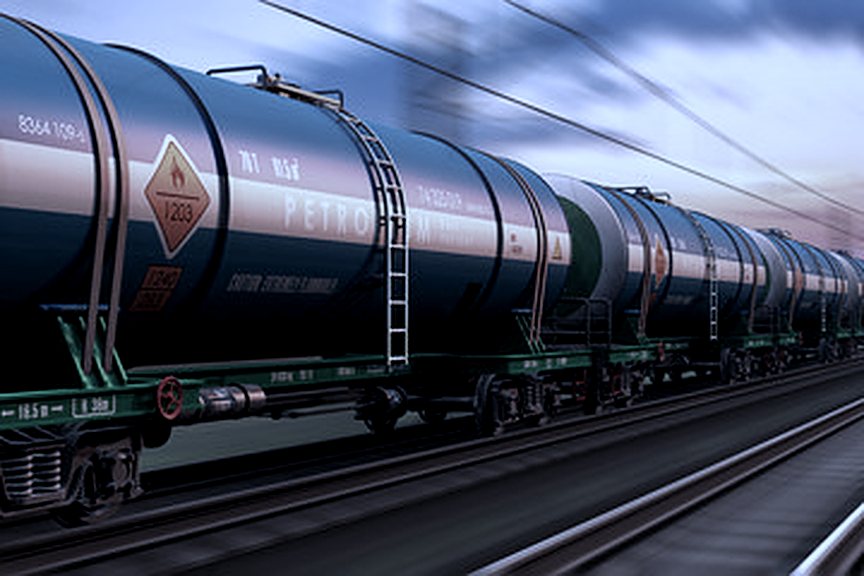
Differentiated midstream, deliberately outside competitive mainstream midstream: islanded markets, adjacent services, and power-integrated CO2.
Bring us a situation.
We look at power, digital infrastructure, water, and midstream opportunities across the United States — as principal, co-developer, or adviser.