Generation, where
scarcity is structural.
Conventional and competitive power across the full United States — merchant markets and utility-dominant regulated jurisdictions alike.
Load growth arrived
before supply did.
The U.S. power market spent two decades planning around flat demand. That assumption is gone. Data center load, electrification, and onshoring have turned interconnection queues and turbine slots into the binding constraints on new supply — and neither responds quickly to price.
The result is a supply-demand imbalance that is structural rather than cyclical. Existing dispatchable generation is worth more than it was underwritten to be, and projects that have already cleared permitting, interconnection, and equipment procurement command a scarcity premium that is real and widening.
NorthPower engages earlier, alongside the developers and management teams doing the work, to structure the path to those milestones — building optionality into permitting, interconnection, and procurement. We also act as adviser to owners deciding what to do with an asset the market has repriced.
Where we focus.
Merchant and contracted generation
Assets and development positions in competitive markets where capacity and energy revenues reflect real scarcity. Contracted revenue is underwritten separately from merchant.
Utility-dominant jurisdictions
Bilateral opportunities in regulated markets — utility-adjacent development, PPA-backed generation, and situations requiring a counterparty who understands rate-base dynamics.
Early engagement, built for optionality
We come in earlier, working with developers and management teams to implement the strategies that maximize the likelihood of success. These strategies are intended to improve execution readiness and preserve multiple potential paths to completion, although development outcomes remain subject to commercial, regulatory and execution risks.
Management teams and portfolios
Platform-level partnerships with operators and developers, structured so capital can move at development speed across a pipeline rather than one asset at a time.
The queue is the
constraint.
Interconnection position, not capital availability, sets the schedule for new supply. We underwrite the position that exists, on the timeline it actually supports.
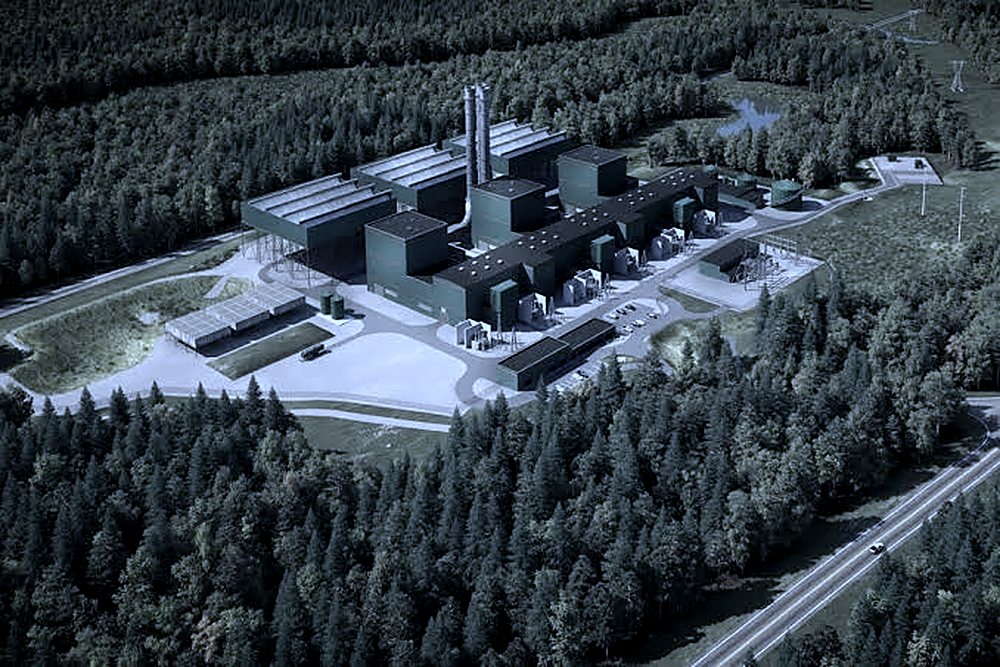
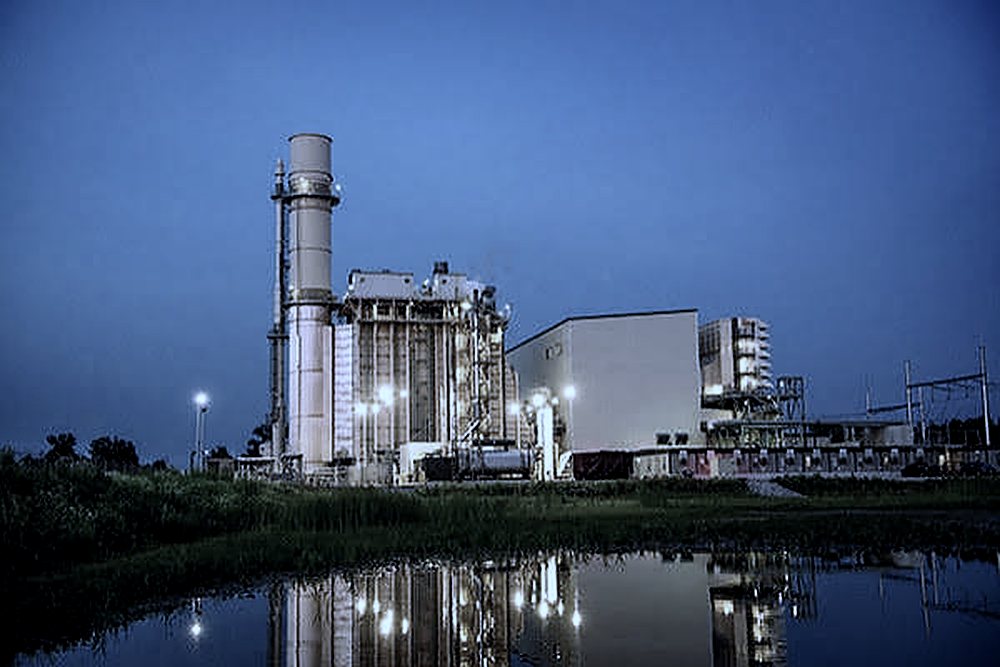
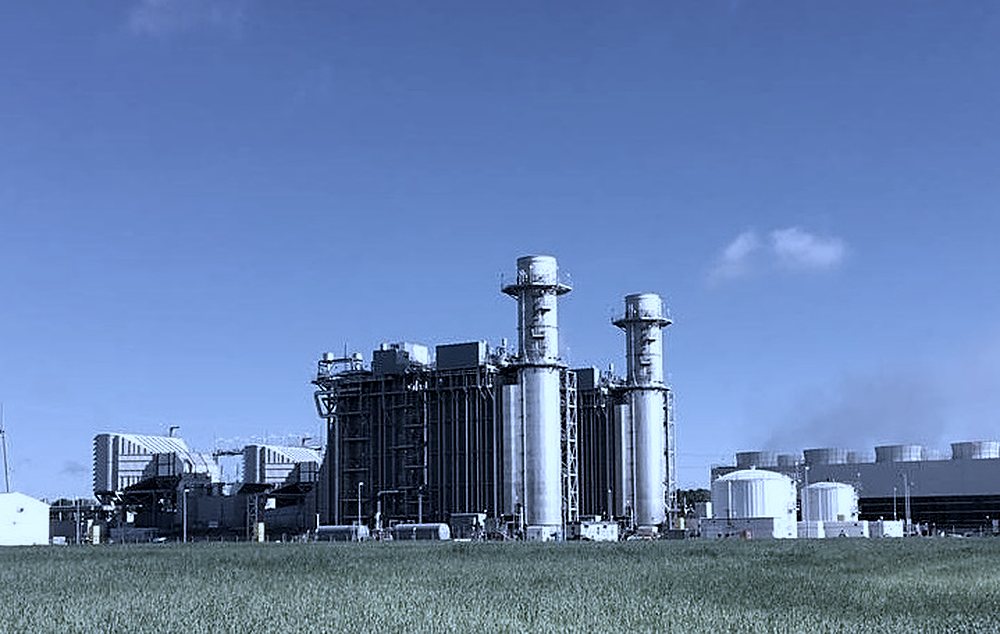
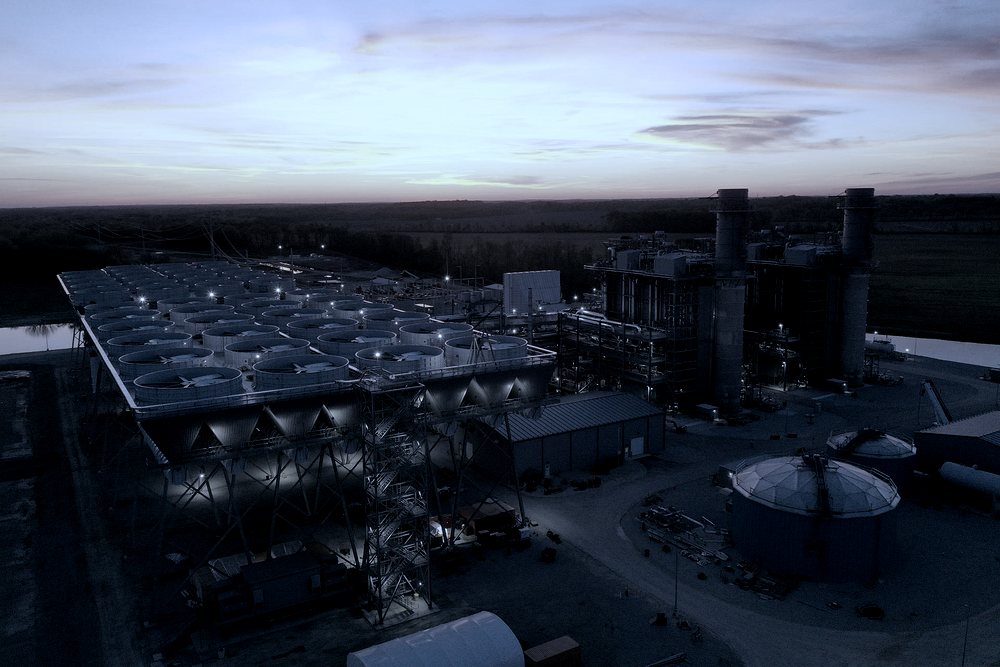
On the ground.
The other three verticals.
Data center power co-development nationwide, spanning competitive and regulated markets. Power-first origination, not confined to a single ISO.
Water treatment M&A — consolidation and platform building in a fragmented, regulation-driven U.S. market.
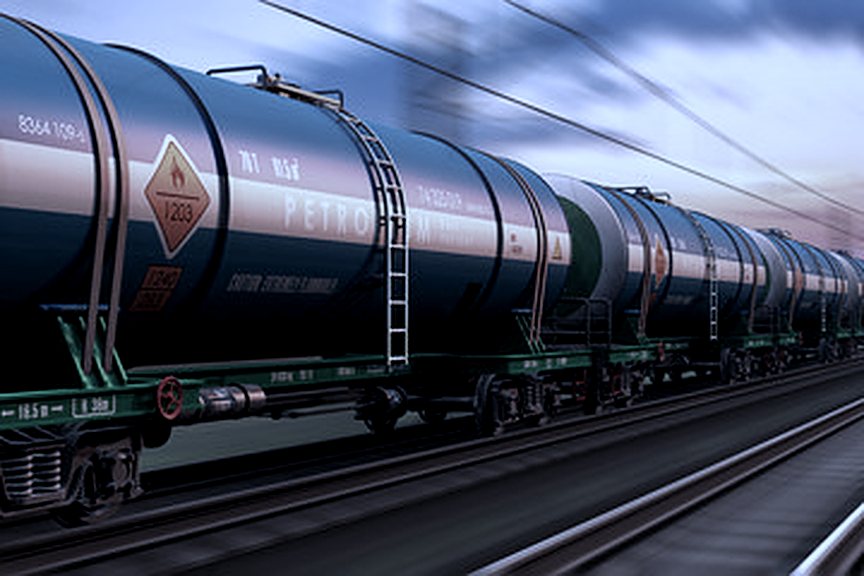
Differentiated midstream, deliberately outside competitive mainstream midstream: islanded markets, adjacent services, and power-integrated CO2.
Bring us a situation.
We look at power, digital infrastructure, water, and midstream opportunities across the United States — as principal, co-developer, or adviser.